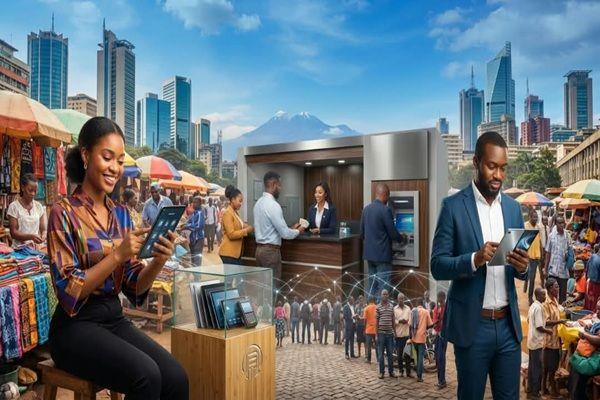
Africa’s banking industry is entering a period of strategic change as established lenders expand into new markets, pursue acquisitions and invest in digital services to reach customers who were previously underserved by traditional banking.
For decades, many African banks concentrated their operations within their home countries, building customer bases around salary accounts, corporate deposits, government transactions and conventional lending. That model is changing as competition intensifies, technology reshapes customer expectations and financial institutions seek new sources of revenue beyond their domestic markets.
The shift is visible in the growing interest of major lenders in East African markets, particularly Kenya, where established local banks are facing increased competition from regional and international players. South African banking groups are exploring opportunities in the region, while Nigerian lenders continue to build their presence across the continent.
For these institutions, expansion is not simply about opening more branches. It is about acquiring established businesses, accessing new customer segments, strengthening payment networks and creating financial services that can operate across national boundaries.
The competition also reflects a broader question confronting African banking: how can lenders turn the continent’s expanding digital economy and demand for financial services into sustainable, long-term growth?
One of the clearest signs of this shift is the growing competition for market share in Kenya. The country has attracted interest from banking groups seeking access to its established financial infrastructure, active digital payments market and position as a commercial gateway to East Africa.
South African lenders, including Nedbank and Absa, have pursued expansion opportunities in the region, while Nigeria’s Access Bank has also been building its continental footprint.
In September 2026, S&P Global Market Intelligence reported that South African banks were looking towards African markets with stronger growth prospects as economic conditions at home encouraged them to diversify their earnings.
The expansion comes with challenges. Banks entering new markets must compete against institutions that already understand local customers, have established distribution networks and maintain relationships with businesses and regulators.
Acquisitions can provide a faster route into these markets, giving buyers access to existing customers, licences, employees and infrastructure. However, successful integration requires careful management of technology systems, credit portfolios, regulatory obligations and differences in business culture.
The risks are particularly important in markets where currency movements, high borrowing costs and economic uncertainty can affect loan repayments and the value of earnings transferred across borders.
For African banking groups, regional expansion offers an opportunity to diversify revenue, but it also demands stronger risk management and a clear understanding of the markets they enter.
Mobile banking applications, electronic transfers, agency banking and mobile money services have changed how millions of Africans access financial services. Customers increasingly expect to transfer money, pay bills, receive funds and manage accounts without visiting a physical branch.
Banks are responding by investing in technology, improving their applications and developing services that can accommodate different customer needs.
The opportunity extends beyond individual consumers. Small businesses, traders, transport operators and informal-sector entrepreneurs require reliable payment systems, working capital and financial products suited to irregular income.
Many of these customers have historically struggled to obtain conventional bank loans because they lack formal employment records, substantial collateral or extensive credit histories.
Digital transaction records can help financial institutions assess some customers who might otherwise remain outside traditional lending systems. However, lenders must still evaluate repayment capacity, protect customer information and avoid relying on incomplete data when making credit decisions.
A March 2026 report by Boston Consulting Group highlighted the next stage of Africa’s fintech development: moving from widespread digital payments towards deeper financial services, including business financing, credit and structured savings.
This transition could create new opportunities for banks willing to develop products for underserved customers rather than concentrating exclusively on established corporate clients and salaried workers.
Yet digital expansion also brings costs. Institutions must invest in cybersecurity, fraud prevention, reliable infrastructure and customer support. A banking application that makes transactions convenient but leaves customers vulnerable to scams or unresolved payment failures can quickly undermine public confidence.
The institutions that succeed will need to combine accessibility with security and dependable service.
For Nigeria’s banking industry, the changing competitive environment presents both opportunities and pressure to adapt.
The country has a large consumer market, an active fintech sector and banking groups with operations extending into other African economies. Nigerian lenders can use these strengths to pursue cross-border business, support regional trade and compete for customers in markets where their expertise is relevant.
However, expanding across Africa requires more than a recognisable brand. Banks must understand different regulatory systems, local currencies, customer behaviour and the economic conditions affecting borrowers.
They must also balance expansion with the demands of maintaining sufficient capital, managing non-performing loans and financing businesses at home.
The strategic question is whether Nigerian lenders can build regional operations that contribute consistently to earnings without exposing their balance sheets to excessive risk.
Technology partnerships could help them compete. Collaborations between conventional banks and financial technology companies can combine established banking infrastructure with digital platforms that already serve large numbers of consumers and merchants.
A recent example is Standard Bank Group’s October 2026 agreement to invest in OPay, subject to the proposed offering and relevant approvals. The institutions also outlined plans to explore opportunities involving digital banking, payments, lending, remittances and the distribution of financial products across African markets.
The proposed collaboration illustrates how the boundaries between traditional banking and digital financial services are becoming less distinct. Banks are increasingly looking beyond their own platforms to partnerships that can extend their reach and improve how customers access financial products.
For Nigerian businesses, stronger regional banking networks could make it easier to receive payments, finance transactions and conduct business with partners in other African countries.
Whether those benefits materialise will depend on the affordability, reliability and accessibility of the services developed.
Africa’s banking opportunity is substantial, but customer growth alone will not determine which institutions build sustainable businesses.
Banks must turn new accounts and digital transactions into profitable relationships while controlling operating expenses, fraud and credit losses. Expanding into a new country can increase revenue, but the cost of acquiring customers, maintaining technology and complying with local regulations can reduce the benefits.
There is also a difference between making financial services available and ensuring that people can use them meaningfully.
A customer who can open an account but cannot qualify for affordable credit remains limited in the financial opportunities available to them. Similarly, a small business that receives digital payments but cannot obtain working capital may struggle to expand its operations.
This is where the next phase of competition could become more consequential. Institutions that understand the needs of small businesses, informal traders, growing companies and cross-border merchants may find opportunities that conventional banking models have not fully addressed.
Regulators will also have a significant role in maintaining confidence as financial services become more interconnected. Effective oversight, transparent lending practices, consumer protection and safeguards against financial crime will remain essential as banks expand their operations.
The broader economic environment matters too. Inflation, currency instability and weak business activity can affect customer spending, loan performance and investment decisions, regardless of how sophisticated a bank’s technology becomes.
The emerging competition is reshaping how African banks define growth. Geographic reach, digital capability, customer data and partnerships are becoming increasingly important alongside the traditional measures of deposits, branches and lending.
For major lenders, the objective is to build businesses capable of serving customers across multiple markets while responding to local economic realities. For smaller institutions, the challenge is to remain competitive by specialising in particular customer segments, developing efficient services or forming strategic partnerships.
The outcome will influence how businesses access finance, how consumers manage money and how easily companies trade across African borders.
But expansion should not be confused with financial inclusion, and a growing digital customer base does not automatically translate into better economic outcomes.
The real test for Africa’s banking industry will be whether its investments produce reliable services, responsible lending and meaningful access to finance for individuals and businesses.
As lenders pursue larger markets and digital customers, the institutions that combine disciplined expansion with a clear understanding of local needs will be better positioned to turn the continent’s financial opportunities into durable business growth.

Administrator contributes reporting and analysis on money for Brandish.
Keep Reading
World Bank mobilises $5.79bn for investment in Nigeria, agric, telecom and SMEs as Dangote, Indorama get funds to boost fertilizer production
How Union Bank nurtures and retains generational customers
OPay, backed by SoftBank, eyes up to US$500 million in New York listing
JP Morgan, largest US bank with $5 trillion in assets to open a merchant bank in Nigeria
Shareholders commend Fidelity Bank’s strong performance following N242 billion in profit after tax and other strong performance indicators
No comments yet — be the first to comment.