By John Ogunlela
Many ways measure a bank's strength.
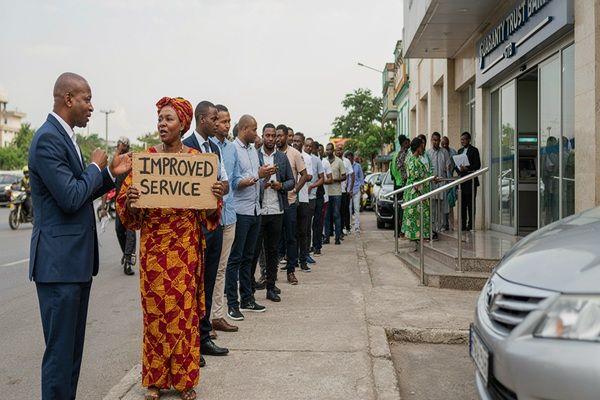
Profitability matters. So do deposits, capital, asset quality and shareholder returns. Regulators have their measures, investors have theirs, and customers often have a much simpler test: can I access my money and carry out my transactions when I need to?
But in an economy like Nigeria’s, there is another measure that deserves more attention: what is the banking system actually enabling people and businesses to do?
It is an important question because banks occupy a particular place in an economy. They do not simply hold money. They connect savings with investment, provide businesses with capital, facilitate trade and payments, and provide much of the financial infrastructure on which commerce depends.
Put more simply, banks are supposed to help money move to where productive activity is taking place.
For the owner of a manufacturing business, that might mean financing to acquire machinery or buy raw materials. A distributor may need working capital to keep goods moving. A farmer or processor may need funding at precisely the right point in the production cycle. An exporter may require trade finance, while a small business may simply need enough liquidity to fulfil a large order without disrupting its day-to-day operations.
These are ordinary business needs, but collectively they tell us something important about the relationship between banking and economic growth.
Where the money goes matters
Nigeria is full of businesses that could do more if they had the means to do so.
The constraints are familiar: high operating costs, power, logistics, access to foreign exchange and repeatedly, access to affordable and appropriately structured finance. Banks cannot solve all these problems, and it would be unreasonable to expect them to.
But they do have an important role in determining which businesses obtain capital and what that capital makes possible.
A loan to a productive company is not simply an entry on a bank’s balance sheet. It can pay for equipment, increase production, support suppliers, finance exports and, in some cases, create jobs. The impact can travel considerably further than the original transaction.
There are examples of this across the banking industry.
Zenith Bank’s 2025 financial statements, for instance, show its participation in financing arrangements intended to channel funds into productive parts of the economy. These include facilities for export-manufacturing activities and the Micro, Small and Medium Enterprises Development Fund, as well as the Non-Oil Export Stimulation Facility designed to support qualifying businesses outside the oil sector.
Access Bank similarly operates a dedicated Business Banking segment focused on SMEs and companies with annual turnover of up to ₦1 billion, combining financing with a broader SME partnership and advisory approach.
Neither example suggests that any one bank has solved the financing challenge facing Nigerian businesses. What they demonstrate is something more useful: that the relationship between banks and the real economy can be seen in where capital is being directed and what customers are able to do with it.
That should increasingly be part of how we judge the contribution of banks.
From providing credit to enabling businesses
Union Bank offers another useful example.
Its current business-banking portfolio covers SMEs, agribusiness and corporate banking, with financing options ranging from short-term cash-flow lending and purchase-order finance to asset finance and longer-term facilities. Its agricultural offering also extends across farmers, processors and other businesses within the agricultural value chain. That tells us what is available. The more interesting question is what it has achieved.
The Bank currently provides N13.811bn in financing to 16 SME agribusinesses across Nigeria’s agricultural value chain, including agricultural production, commodity trading, cocoa, livestock feed, and related sectors. This support strengthens businesses and contributes to real-sector economic activity.
This distinction between offering finance and demonstrating its effect is important.
Almost every bank can point to an SME product, an agricultural finance proposition or a business account. Far fewer conversations ask what happened after the money was provided.
Did the business expand? Did production increase? Were more people employed? Was new equipment purchased? Did the company begin exporting? Was a small enterprise able to become a larger one?
Those are much harder questions, but they are also more meaningful.
There is a tendency to talk about the real economy as though it were an abstract economic concept. It is not. It is the factory producing goods in Ogun, the farmer supplying a processor in Kaduna, the trader moving products across Onitsha, the technology company in Lagos and the thousands of small businesses operating everywhere in between.
The health of those businesses eventually finds its way back into the health of the banking system.
Banking is more than lending
This is another part of the story that is easily overlooked. Businesses do not need banks only when they need to borrow.
They need to receive payments, pay salaries and suppliers, manage cash flow, move money between locations and, in some cases, conduct international transactions. As commerce becomes more digital, the infrastructure behind those activities has become as important as the branch network once was.
A payment that fails for one customer is an inconvenience. Payment systems that repeatedly fail businesses become an economic problem.
This is why investment in transaction banking, payment infrastructure and digital services should also be considered part of a bank’s contribution to the real economy. The ability to move money reliably is itself an enabler of commerce.
For established banks, this is particularly important. Their competition is no longer limited to other traditional banks. Fintech companies and other financial-service providers have changed customer expectations around speed, convenience and accessibility. Businesses now have more choices about who handles different parts of their financial lives.
The implication is straightforward: history and scale may open the door, but usefulness will increasingly determine who keeps the customer.
Union Bank offers another perspective on how established banks are responding to the changing needs of businesses. The Bank currently offers digital business-banking services alongside its SME, agribusiness and corporate propositions. What would make the story more meaningful, however, is evidence of what businesses are actually accomplishing through them.
One supported SME manufacturer has recorded strong business growth since the commencement of its banking relationship, expanding its operations across manufacturing, recycling and related production activities.
Since 2019, the business has grown annual revenue significantly, from ₦5.7 billion to ₦60 billion in FY2025, supported by the Bank’s financing for capacity expansion. Production capacity also increased materially over the period, reflecting the Bank’s role in supporting real-sector growth.
The customer’s expansion into an additional production location has further increased installed capacity, while workforce strength has more than doubled from approximately 1,000 employees in April 2023 to over 2,200 employees as of August 2025.
In addition, the Bank financed key plant and machinery for recycling and related production lines, enabling export activity of over 1,000 tonnes of processed material following completion of the relevant production line.
The obligor’s collateral position has also improved considerably over the relationship period, with plant and debenture assets now valued at an FSV of ₦104 billion, providing adequate coverage for total debt obligations.
A real business story would also make a broader point.
Banks often communicate their contribution to the economy in billions and trillions of naira. Those numbers establish scale, but scale does not always tell the reader what changed. Sometimes one business can.
A manufacturer that adds another production line, an agricultural processor that buys from more farmers, or an SME that moves from ten employees to fifty makes the economic effect of finance easier to understand than a large portfolio number on its own.
What should we expect?
None of this means banks should lend indiscriminately in the name of economic development.
They are custodians of depositors’ money and must manage risk. A bank that sacrifices sound credit judgement in pursuit of lending growth ultimately helps neither its customers nor the economy.
Profitability matters too. Financially weak institutions cannot provide sustainable support to businesses, protect depositors or invest adequately in the infrastructure customers need.
The real question, therefore, is not whether banks should choose between commercial success and economic contribution, because a strong banking system should be capable of both.
We should expect banks to allocate capital responsibly while giving viable businesses a fair opportunity to grow. We should expect them to understand the industries they finance rather than simply sell loans into them. We should expect financial products that recognise how different businesses actually earn and spend money. And increasingly, we should expect the technology and payment infrastructure that allows commerce to happen efficiently and securely.
We should also expect evidence.
When a bank says it supports SMEs, what has that support enabled? When it speaks about agriculture or manufacturing, what businesses have grown as a result? When it talks about financial inclusion, who has been brought into the system? And when it announces billions in financing, what happened after those billions left the bank?
These are not hostile questions. They are the questions that connect banking to its wider economic purpose.
Nigeria needs banks that are financially strong. It also needs businesses that can produce, employ, trade, innovate and grow. The two are more closely connected than we sometimes acknowledge.
Perhaps that is the real economy test for Nigerian banking. It is not simply about how much capital sits on a bank’s balance sheet, but how effectively that capital, infrastructure and expertise help productive activity take place beyond it. Because ultimately, the most useful bank is not simply one that grows, it is one that helps the economy around it grow too.
Ogunlela, a business analyst, writes from Lagos

Administrator contributes reporting and analysis on money for Brandish.
Keep Reading

Nigeria receives billions from its diaspora, but how much becomes productive investment?

JPMorgan deposits N50bn with the Central Bank of Nigeria as American number one bank perfects move for its Nigerian license

Nigeria has Africa's richest man, so why is it still struggling to become a manufacturing powerhouse?

Kenya's mobile money success holds important lessons for Nigeria's fintech industry

Nigeria’s $1.19bn food import bill exposes the business cost of weak local production
No comments yet — be the first to comment.