By Maryaanne Opene
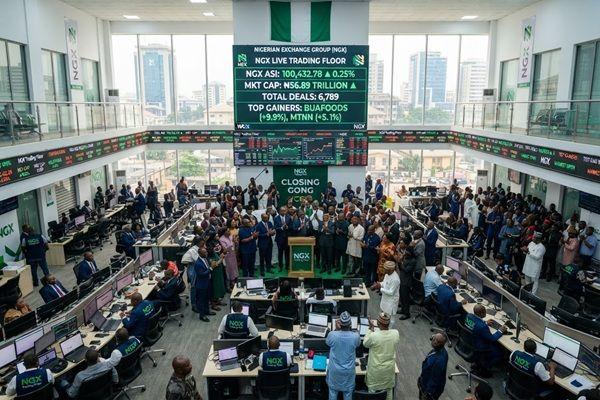
Nigeria's stock market is increasingly being shaped by a handful of corporate giants, raising questions about where investment money is flowing, which businesses are attracting investor confidence and what this concentration means for the country's wider economy.
As of October 13, 2026, ten companies accounted for ₦115.98 trillion, representing approximately 71.15 per cent of the Nigerian Exchange's total equity market capitalisation of ₦163 trillion. The companies span telecommunications, cement, consumer goods, oil and gas, and banking, reflecting the growing influence of a relatively small group of businesses on the country's capital market.
At the top of the market are Airtel Africa, Dangote Cement and MTN Nigeria, followed by major players including BUA Foods, BUA Cement and Seplat Energy. Their positions reflect not only their size but also the importance of the industries in which they operate and the attention their shares attract from investors.
For these companies, scale offers significant advantages. Established distribution networks, access to financing, recognised brands and large customer bases can make it easier to sustain operations and compete in markets where smaller businesses face considerable pressure.
Telecommunications companies benefit from the growing importance of mobile connectivity and data services. Cement manufacturers serve construction and infrastructure markets, while food producers operate in a sector where demand remains essential even as households adjust their spending. Energy companies, meanwhile, provide exposure to an industry closely linked to domestic production and global commodity markets.
These characteristics help explain why large corporations often attract substantial investor interest. Investors seeking exposure to established businesses may find their operating histories, market positions and financial disclosures easier to assess than those of smaller or less frequently traded companies.
However, corporate size alone does not explain a company's market value. Share prices also reflect expectations about future earnings, dividend payments, business expansion and the wider economic environment. A company's market capitalisation is the market value of its outstanding shares, not the amount of cash it holds or the profit it generates.
Liquidity is another important factor. Shares that attract considerable trading activity can be easier for investors to buy and sell, particularly when large sums are involved. This can make established companies more attractive to institutional investors and other market participants who need to enter or exit positions without excessive difficulty.
The resulting dynamic can reinforce the position of already dominant businesses. Greater investor attention can support trading activity, while rising share prices increase market capitalisation and strengthen a company's weight in the overall market.
For Nigeria, however, this concentration creates a distinction between a growing stock market and a broadly thriving business environment.
When ten companies account for more than 70 per cent of listed equity market value, their performance can significantly influence the market's headline figures. Gains among a few major stocks can lift overall capitalisation even when smaller companies experience weaker trading activity or struggle to attract fresh investment.
The reverse is also possible. A significant decline in a few heavily weighted stocks can pull down the broader market, even when other listed companies remain relatively stable.
Consequently, an increase in total market capitalisation should not automatically be interpreted as evidence that all listed businesses are growing or that investment opportunities are expanding across the economy.
The challenge for smaller companies is not necessarily a lack of business potential. Many operate in promising sectors but face obstacles such as expensive financing, limited visibility among investors, weak trading liquidity and the costs associated with meeting listing and disclosure requirements.
These barriers can make it difficult for smaller businesses to compete for the capital that established corporations attract more readily.
A deeper capital market would provide a wider range of credible businesses with opportunities to raise long-term funding, finance expansion and reduce their dependence on conventional bank lending. It would also give investors more choices across industries, company sizes and stages of development.
This matters in an economy where access to capital can determine whether a business expands production, invests in technology, creates jobs or remains trapped at a small operating scale.
Nigeria's growing interest in public investment offers an opportunity to strengthen this relationship between businesses and the capital market. The high-profile public offering of Dangote Petroleum Refinery, for example, has drawn attention to the potential for domestic investors to participate in major industrial enterprises. The broader opportunity lies in encouraging more companies to explore public markets as a source of financing.
Yet attracting investors requires more than a recognisable corporate name. Businesses must demonstrate credible financial performance, sound governance, transparent reporting and a clear strategy for creating long-term value. Investors, in turn, need to assess company fundamentals, valuations and risks rather than assuming that a large market capitalisation guarantees strong returns.
For major corporations, the dominance of the Nigerian Exchange offers visibility and access to a substantial pool of potential investment capital. For the wider economy, the priority should be ensuring that this concentration does not limit the ability of other viable businesses to secure funding and compete.
Nigeria does not necessarily need its largest companies to become smaller. It needs more businesses capable of growing into significant employers, productive enterprises and credible investment opportunities.
The real measure of the country's capital-market progress will therefore extend beyond the rising valuations of its biggest corporations. It will also depend on whether more Nigerian businesses can attract investment, expand their operations and contribute to a market in which opportunity is not concentrated in only a few names.

Administrator contributes reporting and analysis on money for Brandish.
Keep Reading

Nigeria receives billions from its diaspora, but how much becomes productive investment?

JPMorgan deposits N50bn with the Central Bank of Nigeria as American number one bank perfects move for its Nigerian license

Nigeria has Africa's richest man, so why is it still struggling to become a manufacturing powerhouse?

Kenya's mobile money success holds important lessons for Nigeria's fintech industry

Nigeria’s $1.19bn food import bill exposes the business cost of weak local production
No comments yet — be the first to comment.