By Maryanne Opene
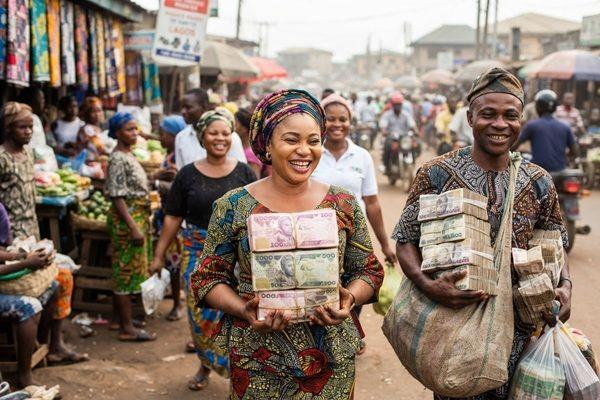
Nigeria’s cashless ambitions are running into a familiar reality: even as digital payments become part of everyday life, billions of naira continue to circulate outside the banking system, sustaining a cash economy that millions of people and businesses still depend on.
The latest monetary data show that cash held outside Nigeria’s banking system rose to ₦4.92 trillion in September 2026, increasing by approximately ₦48.73 billion from ₦4.87 trillion in August. The figure was also 10.3 per cent higher than the ₦4.47 trillion recorded in September 2025.
The increase presents an important question for Nigeria’s financial services industry. Why does physical cash remain so significant when bank transfers, mobile banking applications, point-of-sale terminals and fintech platforms have become increasingly accessible?
The answer lies partly in the structure of the Nigerian economy, where formal financial services coexist with a large informal sector. From market traders and roadside food vendors to transport operators, artisans and neighbourhood retailers, millions of businesses conduct transactions in environments where physical cash remains convenient and widely accepted.
For these businesses, accepting cash is not necessarily a rejection of technology. It is often a practical response to the demands of their customers, the cost of payment services and the reliability of the available infrastructure.
A trader selling food in a local market, for instance, may receive dozens of small payments within an hour. Cash allows the business to complete transactions immediately without depending on network availability, transfer confirmations or the settlement arrangements associated with particular payment channels.
Digital payments offer important advantages, but their usefulness depends on how reliably they work in real commercial settings. A failed transfer, delayed alert or unavailable network can disrupt sales, frustrate customers and force a business to seek an alternative means of collecting payment.
These interruptions matter particularly to small businesses operating with limited working capital. When daily sales provide the money needed to restock goods, pay suppliers or meet household expenses, even a temporary delay in accessing funds can create difficulties.
The cost of receiving digital payments also influences business decisions. Although electronic transfers can reduce the risks associated with handling cash, merchants must consider applicable transaction charges, the cost of acquiring and maintaining payment terminals, connectivity and the time required to resolve disputed transactions.
For businesses with thin profit margins, these expenses can influence whether digital payments are accepted for every transaction or offered alongside cash.
Nigeria’s growing digital financial ecosystem nevertheless demonstrates that the country is not standing still. Mobile banking, instant transfers, digital wallets and agent banking have expanded the ways individuals and businesses can move money without visiting conventional bank branches.
The continued growth of electronic payments alongside substantial cash holdings suggests that both systems can operate at the same time. The amount of currency held outside banks does not, by itself, show how frequently Nigerians use digital payment platforms or whether electronic transaction volumes are declining.
Instead, the figures highlight a distinction between the amount of physical currency people hold and how they choose to make payments. Nigerians can use bank transfers for large purchases, pay bills electronically and still keep cash available for transport, market shopping and other everyday expenses.
This distinction is important for policymakers seeking to reduce excessive dependence on physical currency without excluding people whose circumstances make digital financial services difficult to use.
The Central Bank of Nigeria has set an ambitious direction under its Nigeria Payment System Vision 2028. Its targets include reducing cash held outside banks to below 40 per cent of total currency in circulation and expanding financial inclusion to 95 per cent of the adult population by 2028.
Achieving these objectives will require more than encouraging people to download banking applications or persuading traders to install payment terminals. It will depend on whether the financial system can offer reliable, affordable and accessible alternatives to cash.
The challenge is particularly significant in communities where internet connectivity is inconsistent, electricity supply is unreliable or the nearest banking services are difficult to reach. Some customers may also lack the digital skills, identification documents or confidence required to use formal financial services regularly.
For them, cash is not merely a preference. It can be the most accessible way to participate in the economy.
There is also a business opportunity in addressing these limitations. Financial technology companies, banks and payment service providers can strengthen their market positions by developing services that work effectively for informal traders, rural businesses and low-income customers.
More reliable payment systems, transparent charges, accessible customer support and easier transaction reconciliation could make electronic payments more attractive to merchants who currently depend heavily on physical currency.
Banks and fintech companies also have an opportunity to develop products around the actual needs of small businesses rather than treating them simply as users of payment platforms. Services that combine collections, bookkeeping, supplier payments, savings and access to suitable financing could make digital financial tools more valuable to business owners.
For the government, improving financial inclusion also requires addressing the practical barriers that keep people outside the formal financial system. Affordable connectivity, consumer education, accessible banking services and stronger protection against electronic fraud can help build confidence in digital transactions.
Trust remains particularly important. Customers and merchants who fear losing money through scams, mistakenly completed transfers or unresolved complaints may be reluctant to move more of their transactions online. Effective complaint resolution and clear accountability can therefore be just as important as technological innovation.
The September figures should not be interpreted as evidence that Nigeria’s cashless transition has failed. Cash held outside banks increased during the month, but that movement alone cannot establish the direction of digital payment adoption. It does, however, demonstrate that physical currency continues to occupy a substantial place in the economy.
The immediate priority is not necessarily to eliminate cash but to manage payments in ways that improve efficiency, protect revenue and serve customers effectively. A retailer that accepts both cash and electronic transfers may be better positioned to reach customers with different preferences than one that relies exclusively on either method.
The larger opportunity lies in building a financial system where digital transactions are dependable enough to become the natural choice for more people, rather than an option they use only when circumstances permit.
Nigeria’s ₦4.92 trillion in cash outside banks is therefore more than a monetary statistic. It is a reminder that changing how an economy pays requires understanding how its people work, trade and earn a living. The success of the country’s digital payments ambitions will ultimately depend on whether the alternatives offer practical benefits to the millions of individuals and businesses that keep the economy moving.

Administrator contributes reporting and analysis on money for Brandish.
Keep Reading
NSIA startup awards put focus on turning Nigerian innovation into scalable businesses
The beers are back; International Breweries’ nine-month pre-tax profit rises 22% to N90.44bn
Interswitch, Nigerian banks push phone-tap payments to expand Nigeria’s digital payments market

Dapo Olagunju emerges as pioneer CEO of JPMorgan’s Nigeria operations as CBN grants JPMorgan approval-in-principle

Nigeria receives billions from its diaspora, but how much becomes productive investment?

No comments yet — be the first to comment.